23 Things Nobody Tells You About Living on a Fixed Income
A tax bill, premium renewal, or required withdrawal arrives on its own schedule; your checking balance won't show what's due next.
By Linda Cho, CFP®, Money Editor
Updated · 15 min read
- Written by our money editor
- How we review

Read to the end: #1 is the calendar check that catches a shortfall before a bill comes due, and almost nobody does it.
The insurance renewal sits under a grocery receipt, its new premium printed beside last year's. On the refrigerator, the deposit date hasn't moved. You paid the electric bill yesterday, and the checking balance looked fine then. Now the renewal asks for a full year at once.
A fixed income doesn't make every bill a monthly bill. Annual charges, tax changes, and benefit rules arrive on their own schedules, so a balance that looked safe on Tuesday can mislead you by Friday.
These 23 checks begin with the bills and end with the calendar.
23The insurance renewal beside last year's policy
The new premium makes last year's budget obsolete.
A renewal notice shows what the insurer plans to charge next. Your old monthly transfer doesn't adjust itself when that notice arrives. Look at the premium, deductible, and coverage terms before deciding whether to renew.
Paying the new bill without checking those lines commits money you had assigned elsewhere. The renewal date leaves less room to shop once it passes.
This week, put the old and new declarations pages side by side. Tell the agent, “Show me what changed, including the deductible.”
Then check the bills that arrive with less warning.
22The property tax notice with two payment dates
A tax bill follows the house, not your deposit.
Your assessor's notice shows the property's assessed value; the collector's bill tells you what to pay. If your mortgage servicer pays taxes through escrow, check its records before paying the collector yourself.
A higher assessment and a higher bill aren't the same document. Miss a due date, and your collector's rules determine the charge. Local exemption and appeal rules vary, so get the deadline from the assessor's office.
This week, find both notices and mark their dates separately. Ask the assessor, “What is the deadline and process to challenge this assessment?”
Even a correct bill needs a place in the calendar.
21The escrow statement after a tax increase
A steady mortgage payment can stop being steady.
Your servicer reviews the escrow account against expected tax and insurance bills. If those bills rise, the servicer adjusts future deposits and tells you how it will handle any shortage.
The monthly payment changes even when the loan's principal and interest stay fixed. The escrow statement shows the new payment date, so the old amount on your budget stops being reliable.
This week, read the annual escrow analysis rather than the loan balance. Ask your servicer, “Which bills changed, and when does the new payment start?”
A house also has bills no lender collects.
20The roof estimate you request before a leak
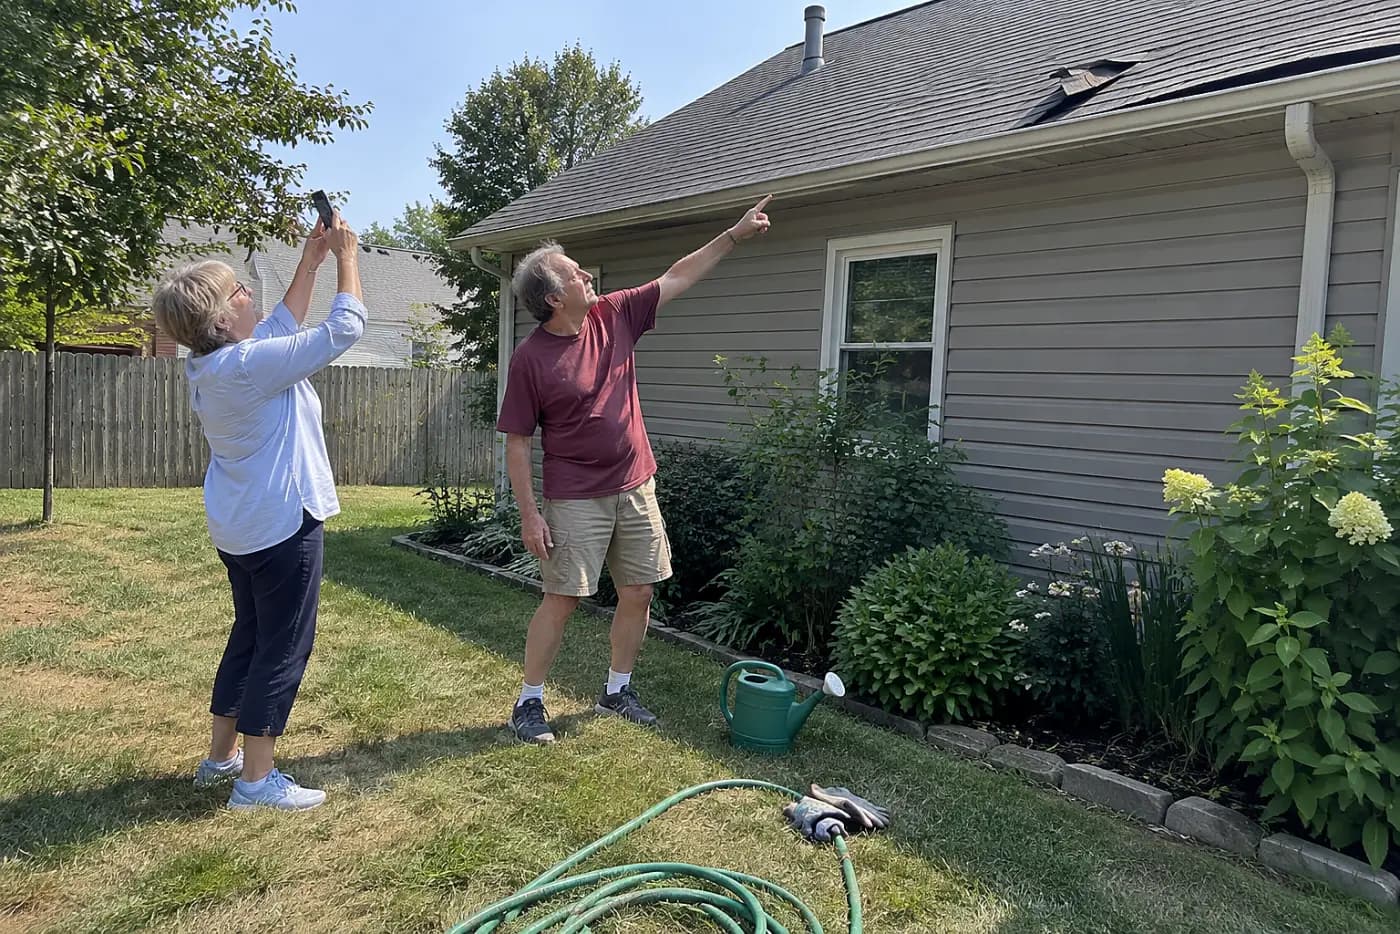
A roof doesn't wait for a benefit increase.
Wear keeps moving while your monthly deposit stands still. A contractor's written estimate gives you a cost to plan around before water reaches the ceiling. Ask what work the price includes and how long the estimate remains valid.
Without that number, a repair fund is just a guess. An urgent job also gives you less time to compare the scope of two bids.
This week, photograph the trouble spots and request written estimates from licensed contractors where licensing applies. Say, “Please separate the repair price from the price for replacement.”
Then look at the smaller charges that repeat all year.
19The streaming charge behind your cable bill
Small subscriptions hide in different billing places.
One service bills your card; another bills through your phone's app store. Deleting an app doesn't end the paid subscription behind it. Your card statement shows who took the payment, while the subscription settings show where to cancel.
A forgotten charge keeps taking a slice of the same deposit. Save the cancellation email or screen in case another charge appears.
This week, mark recurring charges on your bank and card statements. Ask the provider, “What steps end billing, and when will the final charge post?”
Some automatic charges are too important to cancel blindly.
18The autopay date before your deposit arrives
Autopay doesn't check whether your deposit landed.
A company sends its debit on the date you authorized. A benefit deposit follows its own payment schedule, while banks set their own posting and overdraft practices. The transactions cross even when the month's total income covers the month's bills.
An overdraft fee or returned payment takes money from the next bill. A failed debit also leaves you sorting out which company needs to be paid again and when it will retry.
This week, write the actual deposit and debit dates on one page. Tell the biller, “I want to move my payment date; what dates do you offer?”
One missed date matters more when the account has no cushion.
17The bank alert set below your cushion
A balance alert arrives after a problem starts.
Your bank's app sends a message when an account falls below the threshold you choose. That alert doesn't stop a debit or guarantee the balance shown is available. It gives you a prompt to look before another payment leaves.
Set the threshold too low and there's nothing left to rearrange. Set it above your biggest routine debit, then compare the alert with pending transactions before spending.
This week, check the alert settings in your bank app or call the bank. Say, “Help me set a low-balance alert, and tell me which balance it watches.”
Next, make sure the cushion itself has a job.
16The repair envelope inside your checking balance
One checking balance can promise the same dollar twice.
You see cash in the account and decide a purchase fits. But part of that balance already belongs to the car, furnace, or dental bill. The bank sees one balance, not the labels in your head.
A separate savings account or written ledger gives those future bills a visible claim. Neither creates extra income; both stop today's spending from borrowing against a known expense. Write the expense and its expected date beside the amount.
This week, label one savings account or one page for irregular bills. Say to yourself, “This balance includes money already spoken for.”
The hardest expense to plan is the one with no invoice yet.
15The prescription refill before the deductible resets

A familiar prescription can have a different checkout price.
Drug plans set formularies, pharmacy networks, and cost-sharing rules for each plan year. A deductible or coverage change alters what you pay even though the medication hasn't changed. Your plan's Annual Notice of Change identifies updates for the coming year.
The pharmacy counter is a poor place to discover that difference. Don't leave a needed drug behind without calling the plan or prescriber.
This week, compare the notice with your current medication list. Ask the plan, “What will I pay for this drug at my pharmacy next plan year?”
The premium deserves its own check.
14The Medicare premium on your benefit letter
Your benefit increase isn't always your spendable increase.
If Social Security pays your Medicare Part B premium, the premium is normally deducted before your deposit reaches the bank. A change in either amount changes what lands in checking.
Medicare's hold-harmless rule protects certain people from a Part B premium increase that exceeds their Social Security cost-of-living increase. It doesn't cover everyone or every Medicare cost.
That's why a headline about a benefit increase won't tell you your new deposit. Your Social Security benefit notice shows the figures that matter to your account.
This week, compare the gross benefit, Medicare deduction, and net payment on your notice. Ask Social Security, “Please walk me through the deductions between these two amounts.”
Another Medicare bill changes for a different reason.
13The higher Medicare bill after a tax return

Medicare looks back at income you've already spent.
Social Security uses tax information to decide whether an income-related monthly adjustment applies to Medicare Part B and Part D. A prior-year taxable gain shows up later in the premium calculation.
If your income dropped after a qualifying life-changing event, Form SSA-44 lets you request a review. A retirement date alone doesn't erase the bill. The Social Security Administration provides the form and its instructions.
This week, read the reason on any adjustment notice. Ask Social Security, “Does my change qualify for a review using Form SSA-44?”
Tax timing reaches beyond Medicare premiums.
12The required withdrawal marked on your calendar
The tax bill can arrive after the withdrawal.
Required minimum distributions apply to many retirement accounts once you reach the applicable starting age. The Internal Revenue Service calculates the minimum using an account balance and life-expectancy factor. Taking the cash without planning for tax leaves the next deposit doing extra work.
The first distribution has a special deadline, and delaying it puts two taxable withdrawals in one calendar year. A missed minimum triggers an excise-tax question under IRS rules.
This week, ask each retirement account custodian for its required minimum distribution calculation and deadline. Tell your tax preparer, “Please estimate the withholding before I take this money.”
The account you leave untouched needs a separate look.
11The beneficiary name on an old account
An old name can outrank your current will.
Retirement accounts and life insurance policies pay according to their beneficiary designations. The company handling the account uses the designation on file. A will doesn't replace that form.
An outdated name sends the balance according to paperwork you no longer intend. Leaving the field blank sends the company to its account or policy rules instead. Neither outcome follows the instructions sitting in your will.
This week, download the beneficiary confirmation for each account. Ask the company, “Who is listed now, and how do I submit a change?”
Paperwork also controls who helps while you're alive.
10The durable power of attorney in your drawer
A bank needs authority, not family history.
If illness keeps you from handling an account, a relative doesn't gain access simply by knowing your PIN. A financial power of attorney names an agent to act within the document's terms. Banks review the document before accepting instructions from that agent.
An unsigned draft in a drawer won't do the job. State law governs signing, so use a qualified local lawyer if you need a document or a review.
This week, locate the signed document and confirm where the original is kept. Ask your bank, “What would you need to review before my agent could use this?”
Access to records is another gate.
9The bill folder nobody else can find

A helper cannot pay a bill she cannot identify.
Online accounts replace paper envelopes, but the payments keep arriving. Your list of billers, due dates, and account locations gives a trusted person a map without putting passwords on a sticky note.
A missed utility notice becomes urgent before anyone knows it exists. Store the list securely and tell your chosen helper where to find it. Include bills that arrive only once or twice a year.
This week, write down every recurring bill and how it gets paid. Tell that person, “Here's the folder to open if I'm unavailable.”
The mail still brings changes your bill folder won't predict.
8The envelope from your state Medicaid office

An unopened renewal can stop a benefit.
Medicaid and Medicare Savings Programs use income and other eligibility rules set through state processes. The state sends renewal requests to confirm information. If the state asks for documents and gets no response by its deadline, your help with medical costs is at risk.
A Medicare Savings Program helps eligible people with certain Medicare costs. Losing that help changes the money left from a fixed monthly deposit. The Medicaid site identifies the programs; your state notice sets the response date.
This week, open every notice from the state Medicaid office and write its response deadline on the envelope. Ask the number printed there, “What documents do you need from me, and where do I send them?”
A second program has its own paperwork.
7The Extra Help letter about drug costs

Drug assistance needs its own attention.
Medicare's Extra Help program helps eligible people pay Part D costs. Eligibility and review notices tell you what information the program needs. Don't assume a letter about one program covers another, even when both reduce medical spending.
Missing a requested reply puts help with prescriptions at risk. The Social Security Extra Help page describes how to apply and check eligibility. Read the date on your own letter before setting it aside.
This week, find your latest Extra Help notice and read the action line. Ask Social Security, “Do I need to send anything to keep this help?”
Food costs have a different application.
6The grocery receipt beside a SNAP application

A grocery bill rises between deposit days.
SNAP puts money toward food for eligible households. Your state handles the application under federal rules and asks about household circumstances and income. Being on Social Security doesn't, by itself, answer whether you qualify.
The USDA SNAP page directs you to your state's application process. Until you apply, the grocery receipt remains a bill paid entirely from your other money.
This week, find your state SNAP agency through USDA and check its application instructions. Ask the agency, “Which documents should I gather before I apply?”
The same receipt hides a second drain.
5The utility rate printed below usage

Using less power doesn't fix every increase.
A utility bill separates usage from rates and other charges. Your household uses fewer units and still owes more when the rate or fixed charge rises. Comparing totals alone hides which part moved.
Without that split, you cut usage and wonder why the bill barely changes. The bill supplies both figures. Keep two statements together so you're comparing the same charge, rather than guessing from the amount due.
This week, compare usage, rate, and fixed charges on two statements. Ask the utility, “Which charge changed, and what rate plan am I on?”
Heating bills also bring help with their own deadlines.
4The heating assistance application before winter

A shutoff notice is late in the process.
The Low Income Home Energy Assistance Program, or LIHEAP, helps eligible households with heating and cooling costs. States and local agencies set application procedures and work with the funding available to them. Waiting for an emergency narrows the time you have to gather documents.
A high bill alone doesn't enroll you. The federal LIHEAP page points you toward the program; your state agency gives the current application details.
This week, find that agency and ask what it requires before filing. Say, “When does your application period open, and what proof should I bring?”
A bill already in dispute calls for a different move.
3The medical bill before you pay it

A bill isn't proof the insurer finished.
A provider sends a claim, and the insurer processes it under your coverage. The explanation of benefits shows what the insurer paid and what it says you owe. It is not itself a bill.
Paying before those amounts match ties up cash you need this month. Look for a duplicate charge or a claim still marked as pending. The Consumer Financial Protection Bureau has guidance on checking medical bills and dealing with billing errors.
This week, put the bill beside the explanation of benefits. Ask the billing office, “Can you match each charge to the insurer's processed claim?”
When the amount is right, timing still matters.
2The payment plan before an overdue notice

A biller hears from you before its collection system does.
When a correct bill exceeds what's available, ignoring it doesn't change the due date. Contact the provider or utility before the deadline, explain what you can pay, and ask what arrangements it offers. Get any agreement in writing, including dates and the total owed.
A payment plan has to fit around rent, food, medicine, and utilities. An offer that clears one account while emptying checking creates another missed bill.
This week, choose the bill that won't fit and call the number on it. Say, “I can pay this amount on this date; what written arrangement can you offer?”
One calendar check tells you whether that promise holds.
1The thirty-day calendar built from real due dates

A positive balance can already be spent.
The balance on your phone shows money in the account now. It doesn't subtract the rent due Friday, the annual premium due next week, or the prescription refill before your next deposit. Looking only at the balance makes the same dollars appear available for all three.
A thirty-day calendar puts deposits and bills in the order they actually hit. Start with housing, utilities, food, medicine, and insurance. Put irregular bills on their due dates, not in the month you wish they'd arrive. The first day the running balance falls short is the day you need to act.
That date gives you time to move a bill date, call about an arrangement, or hold a purchase. Waiting for a failed payment takes that choice away.
This week, write today's balance at the top of a page and run the next thirty days, transaction by transaction. If the balance turns negative, tell the first biller you need to call, “I'm calling before the due date to discuss a payment arrangement.”
Keep the page open; the next deposit starts another thirty days.
The bottom line
Across all 23 items, the pattern is timing: bills change and arrive before a fixed deposit catches up.
You've prepared when the next thirty days are written down. Irregular bills have a place, and each notice has a response date.
Which of these has already happened in your family?
Bonus: The thirty-day calendar check
- Write today's available checking balance at the top of a page.
- Add each deposit on its expected date; enter every bill on its actual due date.
- Subtract bills in date order, including annual charges and planned refills.
- Circle the first negative balance and call that biller before its deadline.
- Start a new page when the next deposit arrives; don't carry over money already promised.
Linda Cho, CFP®
Money Editor
Linda is a certified financial planner who spent two decades advising retirees before joining Prime Journal.
You might also like