Habits That Quietly Drain A Retirement Account Faster Than You Think
Your retirement account isn't shrinking because of one bad decision, it's leaking through small habits you stopped questioning years ago.
By Linda Cho, CFP®, Money Editor
Updated · 17 min read
- Written by our money editor
- How we review
You check the balance, and it looks smaller than the math should allow. Nothing dramatic happened. No crash, no big withdrawal you can point to and blame.
That's the part that throws people off. Retirement money rarely disappears in one dramatic moment. It leaks out through habits that feel harmless, even responsible, until you add them up over years. Some come from old advice that stopped applying. Some come from avoiding a decision instead of making one. Below are the quiet culprits worth checking before you assume the market did this to you.
1Letting Cash Pile Up In A Savings Account
That account feels safe, and in a narrow sense it is. Nothing about the balance drops overnight, and there is no scary red arrow to watch. That calm is exactly what makes this habit so easy to miss.
The problem is not the account itself but what it is quietly failing to do. Money sitting in cash is not growing anywhere near what it needs to just to keep pace with rising costs. Every year it sits there, it buys a little less than it did before.
Look at what portion of your savings has been parked for years without a purpose attached to it. If there is no near-term use for it, some of it likely belongs somewhere that grows. A conversation with someone who manages money for a living is worth having.
2Skipping The Annual Portfolio Rebalance
Nobody decides on purpose to take on more risk. It happens because the parts of a portfolio that grow fastest quietly take up more space, while the steadier parts shrink as a share of the whole. Nobody signed off on that shift, but it happened anyway.
A portfolio left alone for years stops looking like the one you originally built. What began as a careful mix tilts toward whichever investments have been climbing, which sounds good until those same investments fall. The risk you are carrying is no longer the risk you agreed to.
Set a date, maybe the same week every year, and check the mix against what you intended. Sell a little of what has grown large and add to what has lagged behind. This single habit keeps your risk where you actually chose it, not where the market pushed it.
3Paying For Subscriptions Nobody Uses Anymore
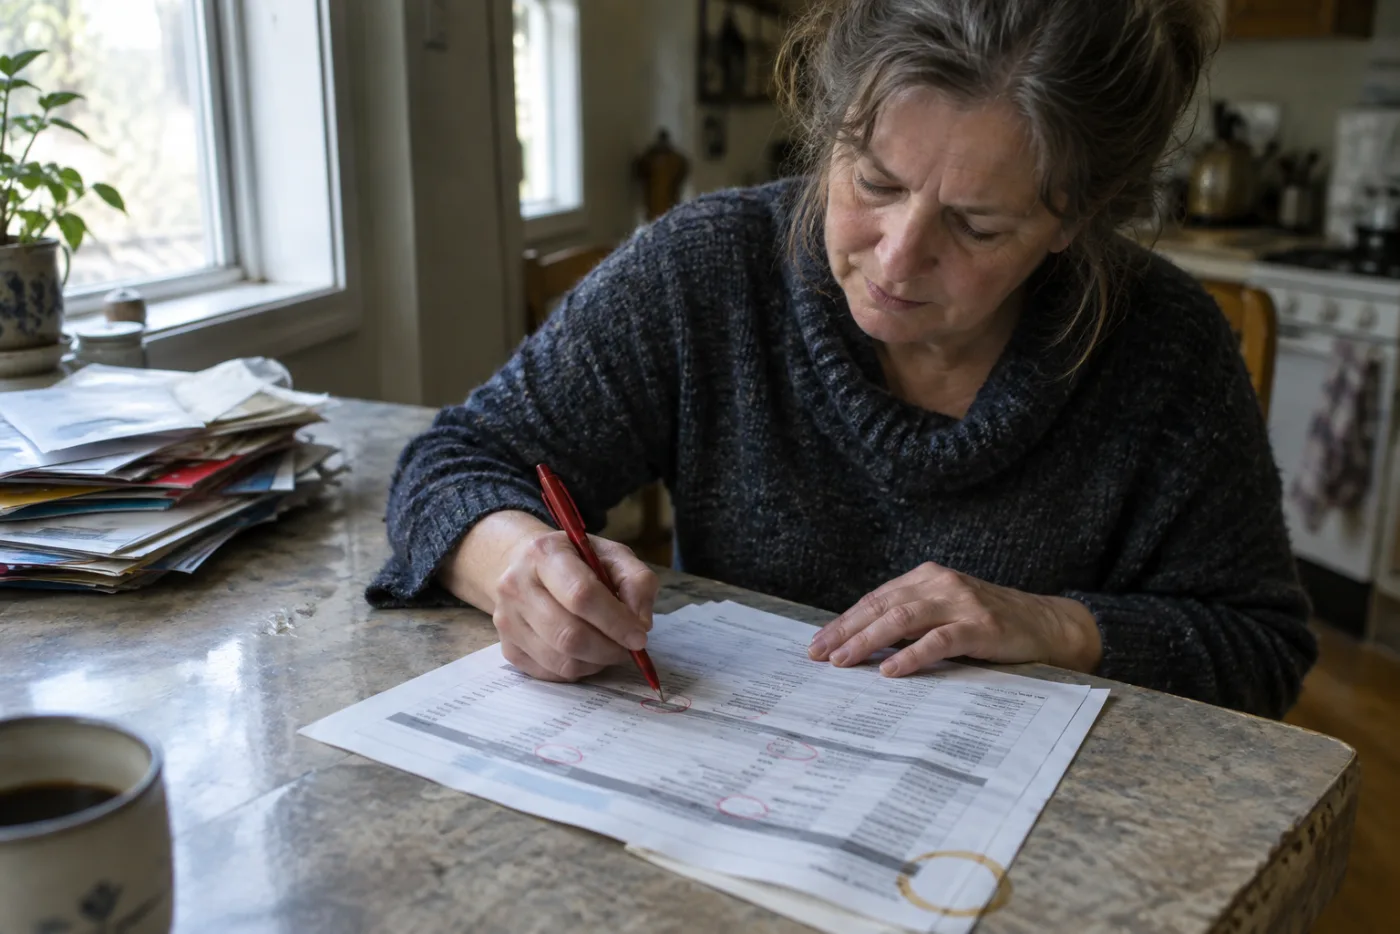
A streaming service you signed up for during a specific show. An app trial that quietly became a paid plan. A membership tied to a hobby you set down without noticing you had.
None of these feels like a financial decision at the time, which is the whole issue. Each one is small enough to ignore on a statement, so it survives review after review simply because it never looks urgent. Years pass and the charge is still there, doing nothing for you.
Go through recent statements and circle anything you could not explain to another person in one sentence. Cancel it the same day you find it, before the habit of ignoring it wins again. Small recurring charges only stay small if you actually stop them.
4Pulling From The Wrong Account First
Retirement savings usually live in more than one type of account, and each type gets taxed on a different schedule. Pulling from the wrong one first can push you into a higher tax bracket sooner than necessary. The order you withdraw in is a decision, even if it feels automatic.
Many people default to whichever account is easiest to access rather than the one that makes the most sense for their taxes over time. That convenience has a cost that shows up later, often in the form of a larger tax bill in a later year. It also shortens how long the whole pool of savings lasts.
Ask whoever handles your taxes to map out a withdrawal order before you retire, not after. The right sequence depends on the accounts you actually hold, so a generic answer will not serve you here. Getting this right once can protect years of income down the line.
5Saying Yes To Every Request From Adult Children
Helping a grown child through a rough patch feels like exactly the right thing to do, and often it is. The trouble starts when a single favor becomes a pattern nobody agreed to out loud. Each request on its own seems reasonable, which is precisely how it becomes a habit.
Retirement savings were built to cover decades, not a series of individual emergencies for someone else's household. Money that leaves quietly for a car repair, then a security deposit, then something else, is money no longer working for your own future. There is rarely a moment where the total is added up.
Decide in advance what you are willing to give and put a shape around it, whether that is a one-time amount or a clear stopping point. Say the boundary out loud before the next request arrives. A number you chose ahead of time is far easier to hold than one invented in the moment.
6Carrying A Credit Card Balance Into Retirement
A balance that rolls over month after month is not a temporary inconvenience. It is a fixed cost working against every other financial decision you make, quietly and without pause. It does not care whether your income just became fixed.
Interest on a carried balance keeps compounding whether markets are up or down that month. Meanwhile, the investments meant to support your retirement are trying to grow against that same headwind. One is working for you, and the other is working just as hard against you.
Paying down a lingering balance before other spending priorities is rarely glamorous, but it removes a guaranteed drag on your finances. Compare the interest rate on the card to any realistic return on your savings elsewhere. In almost every case, the card wins the argument for attention first.
7Letting Insurance Policies Auto Renew
Auto renewal exists so you never have to think about it, which is exactly the appeal and exactly the risk. Insurers count on inertia. A policy that made sense when you first bought it may no longer reflect your situation years later.
Home insurance, auto coverage, even umbrella policies tend to creep upward at renewal without a clear explanation attached. Nobody calls to tell you a better rate exists elsewhere. The bill simply arrives a little higher than it did the year before, and most people pay it without a second look.
Pick one policy each year and get a competing quote before it renews automatically. Bring that quote to your current insurer and ask directly if they can match it. This single habit, repeated once a year, keeps loyalty from quietly costing you more than it should.
8Not Knowing What The Advisor Fee Actually Covers
Many retirees know roughly what they pay an advisor without knowing precisely what that payment buys. That gap is comfortable until it isn't, because unclear fees are the easiest kind to overpay without noticing. Nobody flags a fee that is technically allowed.
Some fee structures layer a management charge on top of fund-level costs you never see listed separately. Each layer looks small in isolation, but together they quietly reduce what actually reaches your account over time. The paperwork rarely makes this easy to spot on your own.
Ask directly for every fee tied to your accounts, in writing, broken out by type. If the answer is vague or delayed, treat that hesitation as information in itself. A clear answer should be simple for anyone managing your money to give you.
9Forgetting About Required Withdrawals
Certain retirement accounts require you to start withdrawing at a set point, whether you need the money that year or not. Missing that window is not a paperwork slip. It triggers a penalty that exists specifically to catch people who forgot.
The confusion usually comes from having several accounts, each with its own rules and its own institution sending separate notices. It is easy to assume someone else is tracking this on your behalf. In many cases, no one is.
Confirm directly with each account provider whether a required withdrawal applies to you and when it must happen. Set a standing reminder well before any deadline, not the week of it. A penalty for missing this is one of the few costs that is entirely avoidable.
10Holding Duplicate Insurance Coverage
It is common to accumulate coverage that overlaps without ever meaning to. A benefit through a former employer, a private policy bought later, and a supplemental plan added somewhere along the way can all quietly cover the same risk. Nobody sat down and compared them side by side.
Paying twice for the same protection feels responsible in the moment, like extra caution. In practice it is money spent for no additional benefit, since a claim can typically only be paid once regardless of how many policies you hold. The second premium is simply a cost with no matching upside.
Lay out every policy you currently pay for and note exactly what each one protects against. Where two policies genuinely overlap, keep the stronger one and drop the other. That single review can free up money currently paying for coverage you already have elsewhere.
11Staying In A House That's Too Big
A house that once made sense for a full household can quietly become a financial weight once it is mostly empty rooms. The mortgage may be paid off, but taxes, utilities, and upkeep do not care how many people actually live there. Space costs money whether it is used or not.
Heating rooms nobody sits in, maintaining a yard sized for a family that has moved on, and repairing systems built for a busier house all draw from the same pool of retirement income. None of it feels dramatic month to month. Over years, it adds up to a quiet redirection of money away from things you would rather spend it on.
Look honestly at how much of the house goes unused in a typical week. If the answer is most of it, a smaller place is worth pricing out seriously, not just discussing. The money freed up can do far more working for your future than it does heating empty rooms.
12Spending Freely In The First Years Of Retirement
The first stretch of retirement often comes with a sense of finally being able to relax and enjoy the freedom. Trips get booked, home projects get funded, and spending loosens in ways that feel earned. It also sets a pace that is hard to walk back later.
The trouble is that early spending habits tend to stick around long after the initial excitement fades. What started as a celebration becomes the new normal, and normal is much harder to shrink than it was to grow. Nobody wants to feel like they are cutting back once they've adjusted upward.
Treat the first stretch of retirement as a trial run rather than a permanent baseline. Watch what you actually spend for a while before assuming that pace can continue for decades. A pace that feels sustainable early on deserves a second look before it becomes fixed.
13Leaving Old 401k Accounts Scattered Behind
Every job change tends to leave a small account behind, sitting untouched at a former employer. Most people mean to deal with it eventually and then simply don't. Years later, there can be several of these scattered across old employers nobody thinks about anymore.
Left alone, these accounts often stay parked in outdated investment choices that were never revisited after the day you left. Fees attached to old employer plans are frequently higher than what you could get consolidating elsewhere. Nobody is actively managing them, because nobody remembers to look.
Track down every old account tied to a former job and decide, deliberately, whether to consolidate them. A single, actively watched account is far easier to manage than several forgotten ones. This is a one-time task that pays off for the rest of retirement.
14Buying Financial Products With Layered Fees
Some financial products are built with more than one fee stacked inside a single purchase. There might be a cost for the underlying investment, another for the insurance-like feature wrapped around it, and a third for the person who sold it to you. Each layer is disclosed somewhere, technically.
The problem is that these layers rarely get explained in plain language at the moment of sale. What sounds like one simple cost is often three, quietly stacked, and each one chips away at what the product actually returns to you. The complexity itself works against transparency.
Before buying anything described as a bundled or all-in-one financial product, ask for every fee listed out separately in writing. If that breakdown is hard to get, treat that difficulty as an answer. Simple products with clear, single costs are usually easier to evaluate honestly.
15Selling Investments Out Of Fear During A Downturn
A sharp drop in account value triggers a very human instinct to stop the bleeding and sell. It feels like taking control during a scary moment. In practice, it often locks in a loss that the market would have recovered from if left alone.
Once you sell during a downturn, that money is no longer positioned to benefit when the recovery eventually comes. You've turned a temporary paper loss into a permanent one, and the smaller base that remains has less power to grow from. The fear is understandable, but the timing is usually costly.
Before making any move during a downturn, wait a set period, even a few days, before acting on it. Talk it through with someone who is not feeling the same panic you are. Decisions made in a calmer moment tend to protect far more of your savings.
16Cosigning Loans For Family Members
Cosigning feels like a favor with no real cost attached, since you are not the one making the payments. Legally, though, you become just as responsible for that debt as the person who actually borrowed it. If they miss a payment, that obligation lands directly on you.
Retirement income is usually fixed, or close to it, which leaves little room to absorb a surprise debt that was never supposed to be yours to carry. A missed car payment or a defaulted loan can quietly become a bill you are now expected to pay. It rarely comes with much warning.
Before cosigning anything, ask what happens specifically if payments stop, not just how the loan works when things go well. If the honest answer would strain your own finances, that is worth weighing seriously. Helping someone should not mean quietly putting your own security on the line.
17Never Updating Beneficiary Designations
Beneficiary forms are filled out once, usually years ago, and then almost never looked at again. Life moves on. Marriages happen, divorces happen, children grow up, and the form sitting on file with an old account provider often does not reflect any of it.
A will does not override an outdated beneficiary form. These designations pass directly to whoever is listed, regardless of what a more recent legal document says. That means an ex-spouse or an estranged relative can end up inheriting an account simply because a form was never updated.
Pull the current beneficiary listing on every retirement account, insurance policy, and investment account you hold. Compare it against who you would actually want receiving that money today. Updating a form takes minutes and prevents a mistake that could otherwise take years to untangle.
18Paying For Extended Warranties And Protection Plans
Extended warranties get offered at the exact moment you are least likely to say no, right after committing to a purchase. They are pitched as peace of mind, and they are priced accordingly. Most of the time, the item in question never needs the repair the plan covers.
Add up how many of these plans have been purchased over the years, on appliances, electronics, even furniture, and the total is usually far more than any single repair would have cost. The plans are profitable for whoever sells them precisely because they rarely get used. That imbalance is the entire business model.
Before agreeing to any protection plan at checkout, ask what the manufacturer's standard warranty already covers. In most cases, it covers more than the salesperson mentions. Skipping the add-on and setting aside a small repair fund yourself usually leaves you further ahead.
19Holding Onto A Timeshare Out Of Guilt
A timeshare often gets purchased during a vacation, in a moment when everything about the trip feels relaxed and generous. Years later, the maintenance fees keep arriving whether or not you have actually used the property. Guilt about the original purchase keeps many people paying long after the appeal has faded.
Selling a timeshare is rarely as simple as selling other property, and that difficulty becomes an excuse to keep paying rather than deal with the hassle. Meanwhile the fees continue, often rising, for a benefit that gets used less each year. The math rarely gets revisited once the habit sets in.
Be honest about how recently the property was actually used compared to what it costs annually to hold onto it. If the gap is wide, look into exit or resale programs built specifically for unwanted timeshares. Letting go of a bad decision is cheaper than defending it forever.
20Ignoring Cheaper Ways To Fill Prescriptions
Prescription costs vary more between pharmacies than most people realize, sometimes for the exact same medication on the exact same day. Many people simply use whichever pharmacy is closest or has always been the default, without ever comparing what else is available nearby.
That loyalty, built on convenience rather than price, quietly costs money every single month for as long as the prescription continues. Over the course of a year, the difference between pharmacies on a recurring medication can be significant. Nobody notices because each individual refill still feels routine.
Ask your pharmacist directly whether a lower-cost option exists for what you take regularly, including generic alternatives or a different pharmacy entirely. A quick comparison call takes a few minutes. For a medication you'll be filling for years, that small effort repeats its payoff every single month.
21Overlooking Tax-Efficient Placement Of Investments
Not every account is taxed the same way, and that difference matters for where specific investments should sit. An investment that generates frequent taxable activity may make more sense inside a tax-advantaged account, while a more tax-efficient holding might belong outside it. Few people ever sort their holdings with this in mind.
When accounts are set up piecemeal over the years, investments often end up placed wherever was convenient at the time rather than where they make the most tax sense. That mismatch creates a quiet drag, paying more tax than necessary on the same underlying returns. Nothing about it looks wrong on a statement.
Review which investments sit in which accounts with someone who understands the tax rules involved. Moving the right holdings into the right account type can reduce the tax bite without changing your actual investment strategy at all. It is a rearrangement, not a risk.
22Keeping An Old Whole Life Policy Out Of Habit
A whole life policy bought decades ago often gets kept simply because it has always been there, not because anyone recently confirmed it still fits your situation. The original reason for buying it, maybe young children or a mortgage, may no longer apply at all.
Premiums on these older policies can be substantial relative to the coverage they actually provide today. Meanwhile, the same money directed elsewhere might do considerably more for your current goals. Nobody revisits the original purchase because canceling a decades-old policy feels like undoing history.
Ask directly what the policy would pay out today and compare that honestly against what it costs you every year to keep. If the numbers no longer make sense for your situation, a financial professional can walk through what replacing or dropping it would actually mean. Habit is not a strategy.
23Letting Small Purchases Multiply Unnoticed
No single small purchase ever feels like a problem. A quick lunch out, a magazine at checkout, a small upgrade here or there, each one is genuinely minor on its own. That is exactly why none of them ever gets questioned.
The trouble is not any individual purchase but the sheer frequency of them, stacking up week after week without ever being reviewed together. Looked at individually, everything seems reasonable. Looked at as a total across a year, the pattern often surprises the very person who spent it.
Pick one recent month and add up every small, easily justified purchase without judging any of them individually. Look at the total, not the pieces. Seeing the sum in one place is usually the first real step toward deciding if the pattern still serves you.
24Never Renegotiating Recurring Bills
Cable, internet, phone plans, and even some insurance premiums are set once and then left alone, often for years at a stretch. Providers rarely lower a rate on their own, because most customers never ask. Silence is treated as satisfaction, whether or not that is actually true.
Meanwhile, new customers regularly get better rates and better deals for the exact same service you have been paying full price for all along. The gap between what a loyal customer pays and what a new customer pays can be considerable, and it grows the longer nobody calls to ask.
Call one recurring provider and ask directly if a better rate is available, mentioning you are considering other options. Many will offer a discount immediately just to keep you from leaving. Repeating this once a year across your bills adds up to real, recurring savings.
25Claiming Social Security Without A Strategy
The decision about when to start claiming benefits often gets made quickly, sometimes just because a milestone birthday arrived or a job ended around the same time. It feels like a formality rather than a major financial choice. In reality, it locks in the size of a benefit you will rely on for the rest of your life.
Claiming earlier than necessary permanently reduces the monthly amount compared to waiting, and that reduction never resets later no matter how long you live afterward. Many people don't realize the decision is permanent until well after it has already been made. There is no do-over once it's locked in.
Before claiming, talk through the timing with someone who understands how the rules apply to your specific situation, including any spousal considerations. A casual decision made in a single afternoon can shape decades of income. This is worth slowing down for.
26Keeping Too Much Money In One Company's Stock
Loyalty to a former employer is a natural feeling, especially after years spent building a career there. That loyalty often shows up financially too, in the form of a large chunk of retirement savings still sitting in that one company's stock. It feels familiar, which is easy to mistake for safe.
A single company's stock carries risk that a broad mix of investments simply does not. If that company struggles, your retirement savings struggle with it at the exact same time, with nothing else in the mix to soften the blow. Familiarity is not the same thing as stability.
Look honestly at how much of your total savings sits in one company's stock, former employer or otherwise. If the number feels large once you actually see it, that is worth addressing directly with someone who manages money professionally. Spreading that risk out does not require abandoning loyalty, just balancing it.
The bottom line
None of these habits feel careless when you're doing them. That's exactly why they work. A quick look at where your money sits, and how it moves, costs you nothing and might explain more than a bad year in the market ever could.
Linda Cho, CFP®
Money Editor
Linda is a certified financial planner who spent two decades advising retirees before joining Prime Journal.
Most read
You might also like